The Nigerian Stock Exchange All Share Index and market capitalisation declined by 4.28% to close the week at 26,216.46 and N13.658 trillion respectively4. This rise was primarily driven by the Financial Services industry, particularly Guaranty Trust Bank Plc, United Bank for Africa Plc, and Zenith Bank Plc, which comprised 82% of the total trade volume valued at N17.2 billion. Despite this, the top six price gainers were mostly non-financial services firms including May & Baker Nigeria, Ekocorp, Neimeth International Pharmaceuticals, BUA Cement, and Ardova Plc. As the equities prices continue to drop, the dividend yields will remain attractive not only to local investors but also to global portfolio managers which will drive improvements in market activities.
The National Bureau of Statistics (NBS) has reported that the GDP growth rate in Q42019 is 2.55% which is relatively higher than Q32019 GDP growth rate at 2.28% and remains the highest quarter on quarter growth since the 2016 recession1. This cumulates to an annual growth rate of 2.27% for 2019. Furthermore, the aggregate GDP for Q42019 stood at N39.5 trillion compared to the aggregate GDP of Q32019 at N37.8 trillion and the corresponding quarter in 2018 at N35.2 trillion. While the non-oil sector shrunk year on year by 0.44%, it contributed 92.68% to Q42019 GDP which is significantly higher than the oil sector’s contribution at 8.78%. As the price of Brent crude oil falls below the US$57 per barrel benchmark in the 2020 budget, this threatens the realism of the budget, thus leading to a slowdown in economic activities. In order to achieve sustainable and significant economic growth, the country’s revenue base should be de-linked from oil, and recurrent expenditure in the form of cost of governance should be cut down. This will allow for the increased revenue to be diverted to key sectors including manufacturing and mining sectors.
The total stock of money in circulation declined at the end of January, falling by 7.9% month-on month from N2.4 trillion in December1. Although the current stock of currency in circulation is 5% higher than the corresponding year, the decline in currency-in-circulation stands to reduce the current levels of inflation2. This potential impact is in line with the expected outcome of the newly increased Cash Reserve Ratio (CRR) from 22.5% to 27.5% which aims to address monetary-driven inflation. The reduction in currency in circulation amid the increase in CRR, which in itself may constrain banks’ ability to create money through lending, may further increase interest rate and cost of doing business. However, the Central Bank of Nigeria’s stance on increasing the loan to deposit ratio from 60% to 65%, which hitherto has recorded some successes in increasing credit to private sector, may continue to further push market interest rates downwards or at least tame the negative impact of increased CRR.
Africa is the world’s least urbanized continent, and yet the rate at which its cities are expanding is growing faster than no other worldwide – at an average of 3.5 percent per year. This growth of urbanization does, however, vary across the continent, ranging from the already heavily urbanized North Africa (47.8 percent) to the least urbanized Sub-Saharan Africa (32.8 percent).The aggregate rate of urbanization on the continent is projected to grow from 40 percent in 2015 to 56 percent in 2050.
The enormous speed at which Africa’s cities are growing is linked to other key development trends, most prominently accelerating economic and population growth, increasing migration from rural to urban areas, and the youth bulge. It is strongly driven by Africans’ perceptions that cities – in contrast to the continent’s rural areas – offer an abundance of livelihood opportunities, including employment and income-generating opportunities, food security, and access to finance, education and social capital as well as social protection.
The 2019 Benchmarking Exercise Report (BER) is produced by the Nigerian Natural Resource Charter (NNRC) in partnership with a consortium of Think Tanks and Civil Society Organisations (CSOs) comprising the Centre for the Study of the Economies of Africa (CSEA), Centre for Public Policy Alternatives (CPPA), We the People: Centre for Social Studies and Development (CSSD),Centre for Social Justice (CSJ), and Social Action (SA).
The 2019 edition is the fourth in a series of BERs produced by the NNRC carried out to provide an assessment of the governance of Nigeria’s petroleum wealth. Three previous exercises were conducted and published in 2012, 2014, and 2017 respectively. The BER uses the NRC framework developed by a diverse set of internationally renowned experts on natural resource management to conduct detailed and contextual assessments of the country’s oil and gas industry. It analyses the governance of petroleum wealth in Nigeria and identifies crucial changes that have taken place in the sector since the last benchmarking exercise was conducted.
The market indices at the Nigerian Stock Exchange (NSE) closed downward in the trading week ended 7th February, 2020. The bearish market recorded a decline in the All-Share Index (ASI) and market capitalization index by 2.69% and 1.61%, closing at 28,067.09 points and N14.618 trillion respectively1. All other market indices depreciated with the exception of the NSE Insurance and NSE Alternative Securities Market (ASeM) Index. The worst hit were the NSE Industrial Good Index and NSE-Meristem Value Index which declined by 4.07% and 3.94% respectively. Significant losses were recorded in both medium and large capitalized stocks such as MTN Nigeria and Nestle Nigeria. Given the global economic slowdown due to the coronavirus outbreak as well as banks reluctance in lending to the real sector, the NSE market is expected to continue on a downward trend. While investors are advised to take advantage of the lower price of equities by purchasing shares of listed companies, the Securities Exchange Commission should adopt more robust and strong regulations, specifically the recapitalization of capital market operators. This will strengthen the resilience of operators and ensure that Nigeria’s capital market is globally competitive.
The manufacturing Purchasing Managers’ Index (PMI) declined in January to 59.2, indicating a 2.63% fall from the month of December1. The slowdown in sectoral expansion was driven by a decline in the non-metallic mineral products, printing and related support activities. Similarly, slower growth was also observed in the non-manufacturing PMI which fell to 59.6, a 5% decline from the preceding month. In the same vein, the Confidence Index (CI) in the month of January which indicates the respondent’s level of optimism on the overall macroeconomy tapered at 28.3 index points. However, the outlook for February is more optimistic at 61.4 index points and is driven mainly by prospects in the service and industrial sectors2. Going forward, we expect that the drop in the PMI will be reversed, at least minimally, as banks continue to lend to the real sector. However, the extent to which the increment will be sustained will depend on inflation levels as well as job creation growth rate in the short to medium-term.
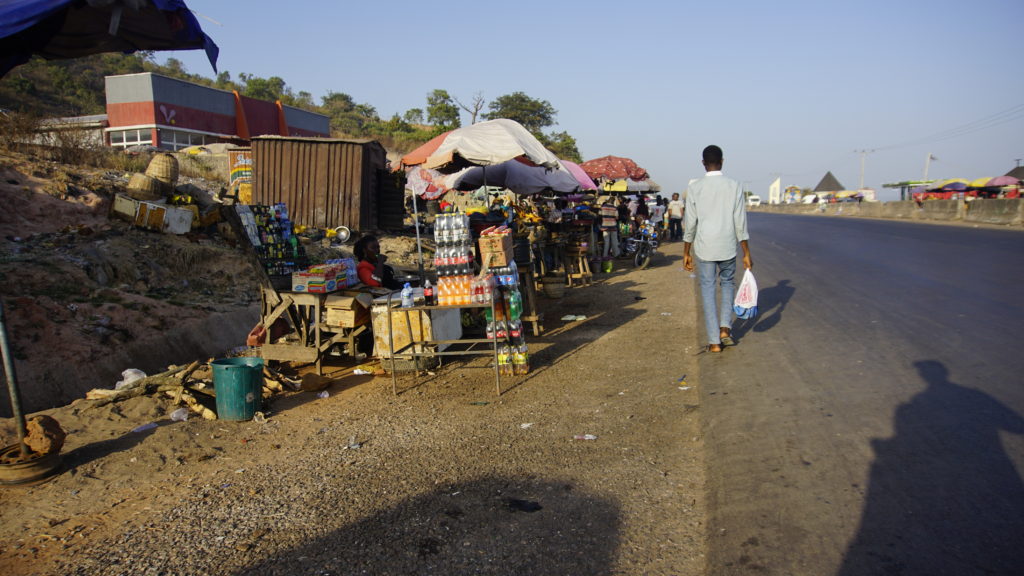
Internal displacement has become an unlikely source of rapid urbanization. Specifically, as people affected by violent conflict in rural areas flee to seek refuge, they are finding cities to be an attractive destination. In Nigeria, violent conflict that leads to displacement mainly occurs in rural areas and locations where the reach of government and its institutions are limited—the seemingly ungoverned spaces enabling perpetrators of violence to operate. Cities, on the other hand, have more government presence and are able to be more resilient to sustained insurgent activities that lead to mass displacement.
Consumer prices for the month of December 2019 increased by 0.13 percentage points from the preceding month which stood at 11.85% 1. This rate was 0.54% percentage points higher than December 2018. The rise in inflation was driven by a rise across all components, with the core sub-index growing by 0.34% to 9.33% and food sub-index by 0.19% to 14.67% over a month. The rise in inflation was driven in part by an increase in access to credit, as indicated in the Central Bank of Nigeria Credit Condition Survey. The survey conducted notes that there was an increase in supply of secured loans to households which was expected to increase in Q1 2020 as well as a rise in overall credit supply to the corporate sector2. Inflation is expected to rise in the coming months given that the closure of the Nigeria-Benin border has driven food prices upwards resulting in cost-push inflation. In addition, the CBN’s directive to commercial banks to give out 60% of their deposits as loans to the real sector could potentially lead to demand-pull inflation. Given that food inflation is at the core of the rising inflation, initiatives should be put in place by both state and non-state actors to increase the productivity of farmers in order to transition farmers from smallholder to large-scale farming.