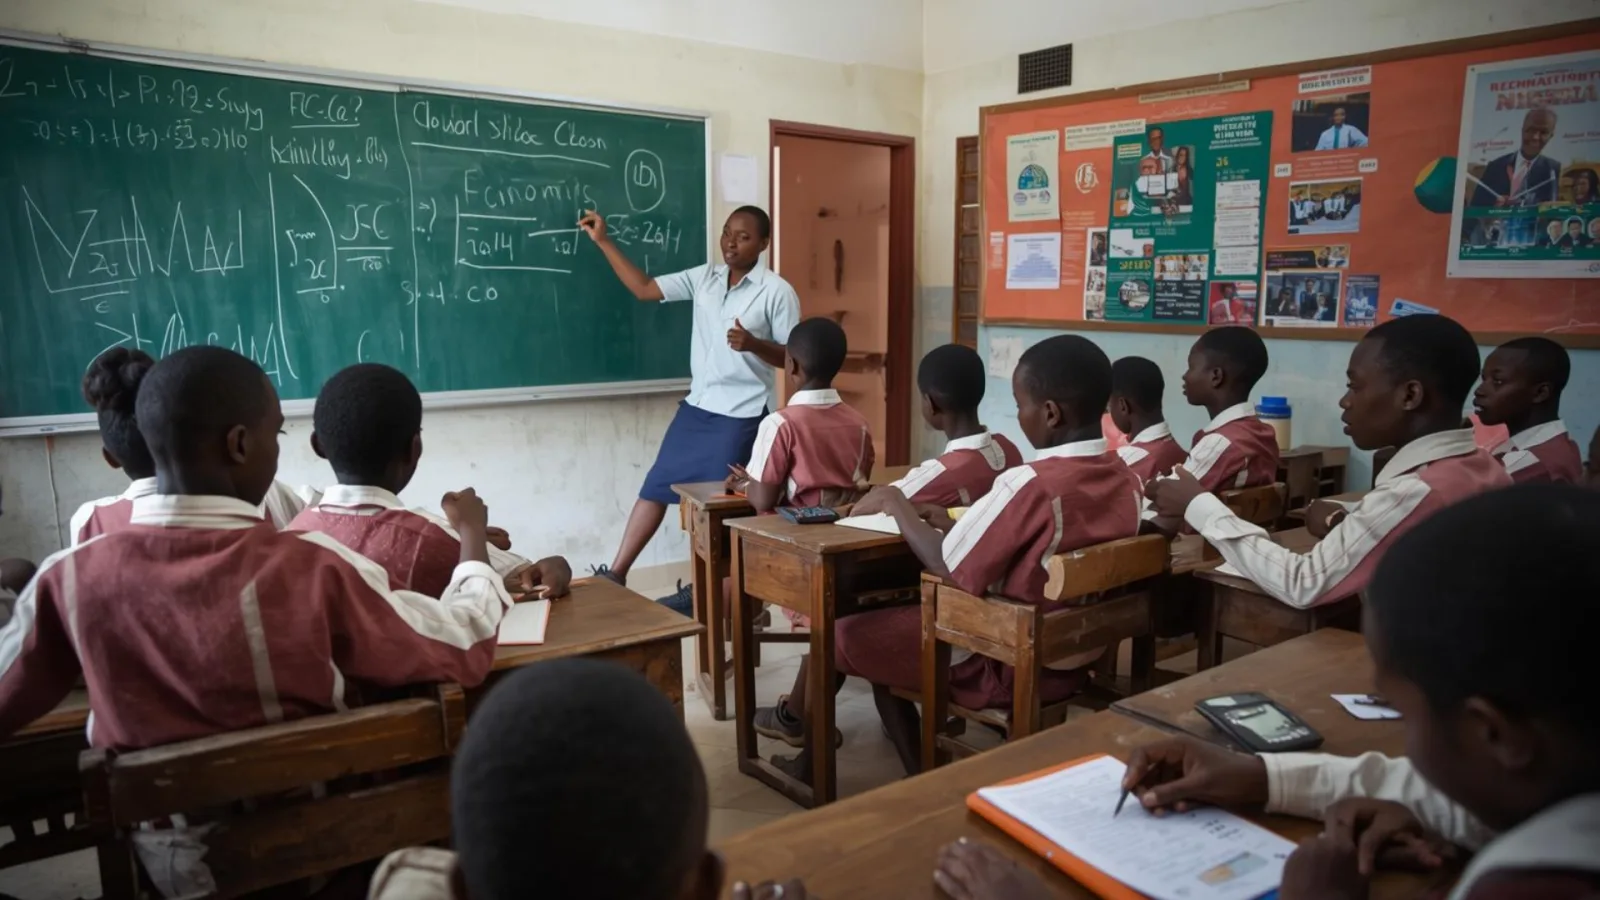According to the National Bureau of Statistics (NBS), the Federation Account Allocation Committee (FAAC) disbursed a total of ₦2.93 trillion to the three tiers of government in November 2025 from the total revenue generated in October 2025. This comprised ₦2.16 trillion from the Statutory Account, ₦49.87 billion from Electronic Money Transfer Levy (EMTL), and ₦719.83 billion from Value Added Tax (VAT). Of the total allocation, the federal government received ₦758.41 billion, state governments ₦689.12 billion, and local governments ₦505.80 billion, while ₦141.39 billion was distributed to oil-producing states from the 13% derivation fund. These allocations reveal that effective revenue mobilisation and timely disbursement are essential for sustaining public service delivery. However, boosting internal revenue mobilisation is very crucial at the subnational level to reduce dependence on FAAC, as most states are largely dependent on FAAC. Thus, there is a need to create an enabling environment for businesses in states to attract investment, which will translate to more tax revenue mobilised at the state and local government levels. To consolidate the current gains in revenue mobilisation, policymakers should strengthen revenue collection efficiency through the digitalisation of tax processes, enhance transparency, and expand non-oil revenue sources. Ensuring there is improved fiscal planning will help stabilise both national and subnational finances, which will support development initiatives across the federation.
Data from the Nigerian Foreign Exchange Market (NFEM), published by the Central Bank of Nigeria (CBN), showed that the naira appreciated by 7.4% in 2025.
A compelling global consensus has formed around achieving Net-Zero emissions as the indispensable framework for collective climate action. This framework, which aims to balance greenhouse gases emitted with those removed from the atmosphere, is grounded in the Paris Agreement's objective of limiting global temperature rise to well below 2°C. It provides a common language and a set of quantifiable targets that shape national policy, international finance, and corporate strategy. The urgency for this framework is clear: between 1990 and 2023, annual energy-related CO₂ emissions surged from 20.5 to 37.3 gigatonnes, with the global per capita average standing at 4.67 tonnes in 2023.
Author: Ezra Ihezie
In Nigeria’s secondary schools, students are typically grouped into one of three subject streams: Science and Technology (Sciences), Humanities (Arts), or Business Studies (Social Sciences). This grouping is typically done at the start of senior secondary school. The system is intended to align students’ education with their intended career paths, ensuring they take subjects required for national examinations, such as the West African Senior School Certificate Examination (WASSCE) and the Unified Tertiary Matriculation Examination (UTME). However, this well-intentioned structure can inadvertently narrow learning opportunities. A prominent example is that students placed in the Social Sciences stream who hope to study Economics at university are often unable to take Further Mathematics, a course where calculus, a fundamental skill for advanced Economics, is first introduced. This results in a likely gap in mathematical preparedness that scholars have called “the mathematics problem”. This challenge is not unique to Nigeria; many Economics students worldwide report being unprepared for the level of mathematical rigour required in their programmes. Evidence from the Economics Network Student Survey in Scotland, for instance, revealed that over 80% of students found their Economics degree involved far more mathematics than they had anticipated. Globally, studies have shown that a robust mathematical background acquired during secondary school is a crucial predictor of academic success and retention for students pursuing Economics at university. For instance, a study in Spain found that students from the Technological stream, which offers Advanced Mathematics, including more extensive math concepts and geometry modules, outperformed their peers from the Social Sciences stream at university, despite being the recommended stream for Economics Business students in secondary school. Similarly, research at the Erasmus School of Economics in the Netherlands demonstrated that science-preparatory students with strong math foundations achieved higher first-year credit attainment (45% vs. 30%) and lower dropout rates (under 25% vs. 45%) compared to non-science students. Collectively, these studies emphasise the essential role of advanced mathematics instruction at the secondary level in enhancing students’ academic outcomes in university Economics programs.
Authors: Obiageli (Oby) Ekwunwa, Adejo Moses Adejo, Chinecherem Jacinta Orji
Can the Chinese economy still be driven by exports in the face of global shocks? This research question is explored in this brief study. Economists and public policy analysts widely asserted that China’s economic growth and development were built on a strong foundation of the export-oriented manufacturing sector (Johnston, 2024). Precisely, China embarked on the mission of export-led growth in the 1980s, marked by a series of economic reforms such as trade liberalisation (particularly joining the World Trade Organization [WTO] in 2001), the reindustrialisation process around 2004 and the processing of export goods (Yao, 2014). However, concerns have emerged about whether the Chinese economy can continue to rely on exports as its primary driver in the years ahead. Roubini (2024) argues that China’s export-led growth model has broken down. He provides a reason for this development. He notes that after three decades of robust economic expansion, during which the economy grew at an average annual rate of 10%, China’s growth has slowed significantly. Currently, the growth rate hovers around 5% and the International Monetary Fund projects that it could decline further to approximately 3.4% by 2028 [1]. Roubini attributes this economic outlook to structural, rather than cyclical problems. These include an ageing population, a collapsed real estate bubble, massive overhangs of private and public debt and a marked shift away from market-oriented reforms back to state capitalism.
This study used JKS Granger non-causality and 3SLS to examine causal interactions among tourism arrivals, environmental pollution and health outcomes in Africa. The causality results revealed a Granger-caused relationship between tourism arrivals, environmental pollution, and health outcomes. The 3SLS results indicated that tourism is positively linked with health outcomes and environmental pollution, while tourism and health outcomes are also positively related to environmental pollution. Our findings suggest that the government should prioritise sustainable tourism.
In November 2025, the National Bureau of Statistics reported a gradual easing of annual price pressures alongside continued short-term increases in consumer prices. The Consumer Price Index (CPI) rose to 130.5, up from 128.9 in October, indicating a sustained increase in the general price level of goods and services purchased by households. Nonetheless, headline inflation moderated to 14.45%, down from 16.05% in the preceding month, reflecting a slowdown in year-on-year inflation. Compared with November 2024, headline inflation was 20.15%, a significant improvement largely driven by base effects following the rebasing of the CPI. Despite this moderation in annual terms, month-on-month inflation increased to 1.22% from 0.93% in October, signalling that underlying inflationary pressures persist. This suggests that households continue to experience rising costs in the short term, particularly for essential goods and services, even as broader inflation indicators show signs of improvement. The divergence between easing year-on-year inflation and rising month-on-month inflation highlights the need for continued policy vigilance. While inflationary conditions have improved relative to the previous year, achieving durable price stability will require addressing structural constraints such as food supply disruptions, energy costs, and distribution inefficiencies, alongside sustained macroeconomic discipline.
The Organisation of the Petroleum Exporting Countries’ (OPEC) November Monthly Oil Market report indicated that Nigeria’s average daily crude oil production (based on direct communication) for October 2025 increased by 0.8% (11,000 bpd), rising from 1.390 million barrels per day in September to 1.401 million bpd in October 2025. Despite this modest increase, production remained 6.6% below Nigeria’s OPEC quota of 1.5 million bpd and 31.9% below its target of 2.06 million bpd. These gaps indicate that Nigeria continues to face challenges in fully restoring crude oil production, despite recent investments and government-led efforts in the upstream sector. Falling short of its OPEC quota puts pressure on foreign exchange earnings, given that the sales of crude oil remain the country’s primary revenue source. However, the slight increase in output indicates a cautious yet promising recovery, which could enhance fiscal conditions if the momentum is sustained. To build on this progress, Nigeria should focus on repairing and upgrading critical oil infrastructure, securing production sites against vandalism and oil theft, and attracting consistent investment to boost output and move closer to its production targets. ECONOMIC SNAPSHOT + Quarterly Indicators
According to the Central Bank of Nigeria’s Purchasing Managers’ Index (PMI) report, Nigeria’s Composite PMI increased from 55.4 points in October 2025 to 56.4 points in November 2025. This increase marks twelve consecutive months of expansion, representing the strongest indication of private- sector growth so far in 2025. In the month under review, the industry sector PMI stood at 54.2 index points, while the service sector PMI rose to 56.8 points, up from the 55.6 points recorded in the previous month. Similarly, the agricultural sector expanded for the sixteenth consecutive month, standing at 58.2 index points, an increase from the 55.7 index points recorded in October 2025. The rise in private-sector activity was driven by higher production and increasing demand, signalling a broad-based strengthening of economic activity across all sectors. This positive trend also suggests that the increasing demand is likely to stimulate further production, raise employment levels, improve household incomes, and strengthen overall consumer confidence. However, this expansion carries potential inflationary risks and may affect affordability and broader economic stability. To mitigate these risks, efforts should be made to support small and medium-sized enterprises by providing access to affordable credit and capacity- building programmes. Furthermore, given the significant growth recorded in the agricultural sector, the government should invest in agricultural technology and improve value chains to enhance productivity and export capacity.