Publications

Follow via RSS

Drivers of Disparity: How Policy Responses to COVID-19 Can Increase Inequalities

Countries across the world have deployed macroeconomic policies to address the negative economic implications of the COVID-19 pandemic and subsequent lockdown measures.

Recommendations:

  • Divert newly available resources (such as unused travel allowances) and leverage funding from the private sector and/or international partners, sovereign wealth funds, national reserves and other sinking funds to increase allocations to pro-poor sectors. In the long term, the tax capacity of Nigeria and Uganda should be improved.
  • Use electronic platforms to distribute cash to hard-to-reach populations such as informal sector workers and low-income households. National databases such as voters’ rolls, social registers and household surveys can be used to identify vulnerable people.
  • Promote investment in renewable energy, particularly for low-income households. Areas that are too remote to be connected to the electricity grid would also benefit from decentralised energy sources.

Executive summary

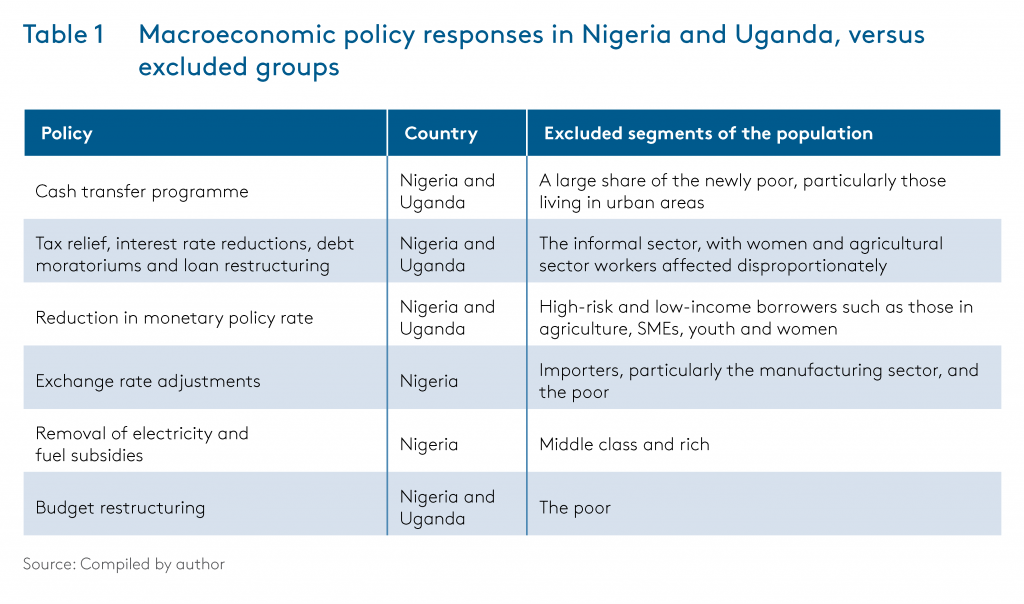
Countries across the world have deployed macroeconomic policies to address the negative economic implications of the COVID-19 pandemic and subsequent lockdown measures. However, these policies can have different outcomes for various segments of the population. This policy briefing assesses the channels through which macroeconomic policy responses in Nigeria and Uganda negatively affect or exclude specific groups, with the aim of resetting policies to achieve more inclusive outcomes that will support economic growth and development in the post COVID future. It finds that the urban poor and the informal sector are being excluded as a result of the poor coverage of cash transfer programmes and the implementation of policies mostly applicable to the formal sector. Loans to low-income borrowers are not likely to increase despite downward revisions to the monetary policy rate, while importers and poorer households will be the worst hit by exchange rate adjustments in Nigeria. While the middle class and rich are affected by the removal of subsidies in Nigeria, those living in poverty do not benefit from the budget restructuring in Uganda.

Introduction

While economic recessions can have significant distributional effects, the macroeconomic policies adopted to counteract recessions can have varying outcomes on different segments of the population. As such, a government’s policy responses to the COVID-19 pandemic can increase inequalities through key transmission channels. Data from the International Monetary Fund’s Policy Response Tracker shows that 89% of African countries have deployed fiscal stimuli for vulnerable populations, including those who have lost their livelihoods as a result of the crisis and low-income households. Liquidity has been provided to affected businesses and sectors such as tourism, hospitality and aviation in 92% of African countries.1Yet the design and implementation of such macroeconomic policies are often neutral, thus allowing existing forms of inequality to worsen. This policy briefing assesses the ways in which macroeconomic policy responses in Nigeria and Uganda negatively affect or exclude specific groups, particularly youth, women, the informal sector and the newly poor (especially in urban areas). In addition, businesses in the agricultural and manufacturing sectors, as well as small and medium-sized enterprises (SMEs), are negatively impacted by these policy responses. The aim of this policy briefing is to help reset policies to achieve more inclusive outcomes that will support economic growth and development in the post-COVID future.

The analysis covers the fiscal and monetary policies deployed by the Nigerian and Ugandan governments and shows how these policies could lead to worse outcomes for certain segments of the population. The dimensions of disparities considered for individuals include age, gender, place of residence (rural or urban) and income category; for businesses the dimensions include size of business and sector (agriculture, manufacturing and services).

Key findings

Poor coverage and cash transfer targeting exclude the urban poor. Both Nigeria and Uganda have expanded existing cash transfer programmes to deliver funds to the poor and those most vulnerable to the pandemic. Nigeria has scaled up its programme by increasing its National Social Register of poor and vulnerable households by 1.1 million households to 3.7 million households (15.5 million individuals).2The government gives NGN35,000 ($13) per month to the poorest households for at least three years to ensure food security. Similarly, since the pandemic the Ugandan government has increased funding for the Urban Cash for Work Programme (UCWP) to UGX4130 billion ($35 million) and social welfare programmes by UGX 152 billion ($41 million), with an additional UGX 45 billion ($12.03 million) for government relief aid in response to COVID-19 and another UGX 107 billion ($28.6 million) for the Social Assistance Grants for Empowerment (SAGE), targeting the elderly.5Under SAGE, each beneficiary is paid UGX 25,000 ($6.7) per month. The programmes have also been expanded, with the UCWP covering an additional 500 000 individuals and SAGE an additional 71 districts.6

Despite these expansions, these cash transfer programmes underperform significantly in terms of size, coverage and targeting. At 0.002% and 0.00017% respectively, spending on cash transfer programmes as a share of gross domestic product (GDP) in Uganda and Nigeria is meagre.7As a result, the programmes’ coverage falls significantly short. Based on the 2019 Nigerian Living Standards Survey (NLSS), about 83 million Nigerians are living in poverty, implying that 81% of poor people are excluded from the National Social Register.8Similarly, in Uganda 10 million people are living in poverty, based on the household survey in 2016/17.9However, only 1.5 million people benefited from the UCWP.10Furthermore, the amounts allocated do not cover the cost of a basic nutritious diet per month for a household of five.

Given the strategy of identifying poor households in Nigeria – using the National Social Register to select the poorest 30% of households in states with high poverty levels – the beneficiaries are mostly members of agrarian and rural communities. Yet the newly poor in urban areas, such as SME owners, drivers and cleaners, are most susceptible to income shocks caused by the pandemic, making the targeting of the cash transfer programme sub-optimal. Even in Uganda, the majority of the additional funds is targeted at the UCWP and SAGE. However, the former is likely to experience delays owing to the pandemic and the elderly are not particularly prone to income shocks from the pandemic. In addition, the eligibility age for the SAGE programme was increased from 65 to 80 years, thus reducing the size of the target population.

Most of the policies deployed – tax relief, interest rate reductions, debt moratoriums and loan restructuring – do not impact the informal sector, affecting women and agricultural workers disproportionately. While both countries are using a range of policies to mitigate the impact of the pandemic on individuals and businesses, these policies mostly benefit formal sector workers and businesses. Yet the informal sector accounts for 65% and 50% of Nigeria and Uganda’s GDP respectively, and employs 80% of the labour force in both countries.11Although not all informal workers are poor, they face a higher risk of poverty, are more susceptible to income shocks than their counterparts in the formal sector, and live in urban areas with higher living costs and little recourse to subsistence agriculture. With women accounting for 74% of workers (non-agriculture)12in the informal sector in subSaharan Africa, and the agricultural sector contributing significantly to the informal economy, women and those who work in agriculture do not benefit from these relief policies.

Downward revisions to central banks’ policy rates have failed to reflect in the lending rate of commercial banks, particularly affecting high-risk and low-income borrowers such as small-scale farmers, SME owners, youth and women. Expansionary monetary policies have been adopted, with the Central Bank of Nigeria reducing its monetary policy rate from 13.5% to 11.5% and the Bank of Uganda reducing its rate from 9% to 7%.13However, interest on loans made by commercial banks remains high, affecting high-risk and low-income borrowers. Owing to externally determined conditions such as weather and price volatility, workers in the agricultural sector are widely viewed as high risk, making it difficult to reduce the lending rate offered to them. In addition, segments of the population with low income and limited access to collateral such as SME owners, youth and women are less likely to be offered favourable loan terms.

Exchange rate adjustments in Nigeria are having a direct negative impact on importers and an indirect impact on poorer households through rising domestic inflation. With crude oil contributing about 80% of foreign exchange earnings,14the foreign exchange shortage owing to the decline in demand for oil has put pressure on the exchange rate, leading to the devaluation of the naira. The official exchange rate was first adjusted from NGN 307/$1 to NGN 361/$1, and then to NGN 380/$1.15These revisions have led to a rise in the price of imports, particularly affecting the manufacturing sector, which is heavily dependent on imported raw materials and intermediate goods. As a result, domestic prices are rising, with implications for the purchasing power of poor citizens.

Removal of electricity and fuel subsidies is having a disproportionate impact on the income of the middle class and rich. As a result of the pandemic, the Nigerian government has increased the fuel price from NGN 121 ($0.32) to NGN 162 ($0.43) per litre. The electricity tariff has gone from NGN 30.23 ($0.08) to NGN 62.33 ($0.16) per kwh (for consumers with an electricity supply above 12 hours per day). The drop in government revenues necessitated the removal of these electricity and fuel subsidies. Given that poor households were not the main beneficiaries of these subsidy programmes – 43% of Nigerians, mostly those living in rural areas, do not have access to electricity16and low-income households use relatively less fuel and electricity – the subsidy removal is likely to reduce the disposable income of the middle class and rich.

Budget restructuring in Uganda does not support those living in poverty. Neither the supplementary budget passed before the end of the 2019/20 fiscal year nor the 2020/21 budget caters adequately for those people most affected by the pandemic. The main beneficiaries of the supplementary budget are SMEs able to access funds from the Uganda Development Bank (UGX 455 billion [$122.1 million]) and suppliers of goods to government through the clearing of domestic arrears (UGX 223 billion [$59.9 million]), with allocations to social protection coming in third at UGX 105 billion ($28.2 million).17Similarly, the sectors with the biggest increases in budget allocation in 2020/21 are water and environment (35%), science, technology and innovation (30%), local government (28%) and public administration (26%).18Even in Nigeria, the 2020 budgetary allocations to works, power and housing; agriculture; and information and communications increased relative to the 2019 budget, while there were reductions in the allocations to education (16%), health (11%) and humanitarian affairs (12%).19
Conclusion

Existing forms of inequality can deepen in the face of a major crisis such as the COVID-19 pandemic – and as a result of the neutrality of policies deployed in response to the crisis. The macroeconomic policy responses of the Nigerian and Ugandan governments have had the unintended effect of excluding youth, women, the informal sector and the newly poor (particularly in urban areas). At the same time, the removal of electricity and fuel subsidies are affecting the middle class and rich disproportionately, given that these groups were the beneficiaries of the initial subsidy programme. In addition, businesses in the agricultural and manufacturing sectors, alongside SMEs, are likely to be negatively affected by some of the policy responses.

Excluding a wide range of the population will not only affect present living conditions and wellbeing but also limit the private sector spending required to stabilise the economy and avert or recover from a recession. While the governments of both countries have increased spending in order to counteract the drop in private sector consumption and investment, taking on debt for this purpose, debt sustainability remains a pressing issue. As evidenced by their current budgets, debt servicing takes up a considerable amount of government revenue with implications for development spending.

In future, response strategies should be context-specific and take into consideration existing inequalities in order to provide a more tailored and inclusive approach. This will ensure that all segments of the population are reached, lead to efficiency in spending and limit negative welfare impacts.

Governments should revise their budget allocations to healthcare and social protection in order to address the needs of vulnerable people and affected businesses. In the short term, this can be done by using newly available resources (such as unused travel allowances), funding from the private sector and/or international partners, sovereign wealth funds, national reserves and other sinking funds. In the long term, the tax capacity of both countries needs to be improved to allow government to mobilise adequate domestic resources to meet current needs and build fiscal buffers.

Given the widespread access to mobile phones and the ease of electronic transfers, both countries should adopt electronic platforms to distribute cash to hard-to-reach populations. Countries that used electronic transfers extensively before the pandemic, such as Kenya, have been able to use these platforms for cash payments during the pandemic. National databases can be used to effectively identify vulnerable people.

According to the International Renewable Energy Agency, half of new solar and wind installations are cheaper than fossil fuel energy sources,20making renewable energy more affordable on average. Thus, promoting investment in and use of renewable energy is crucial, particularly for low-income households.

Acknowledgment

The author is grateful to Dr Susan Kavuma for peer reviewing this policy brief.

This article was first published at Compra

Read More

FARMER PERCEPTION OF CLIMATE CHANGE STRESSORS: ADAPTATION STRATEGIES AND EFFECT ON FARMER STRESS-MIGRATION

Study investigated the effect of farmer perceptions of climate change stressors on stressmigration using primary data collected by means of multi-stage sampling technique in 2012 on 120 irrigated upland rice-farming households. Data were analyzed using descriptive statistics and Heckman Two-Steps probit models. Results showed that drought and flood principally reduced rice yield, led to high crop loss, increased food insecurity and indebtedness and induced farmer stress-migration. Twenty-two percent of the farmers adapted to stress-migration between the years 2007 to 2011.

This article was first published here: International Journal of Agriculture, Environment and Bioresearch

Read More Download PDF

Continental Integration & the Nigerian Economy

The Effect of the African Continental Free Trade Area on Medium Small and Micro-scale Enterprises in Nigeria

                The roadmap towards a regionally integrated Africa formally commenced with the signing of the African Economic Community (AEC), also known as Abuja Treaty, in June 1991. The Treaty established the building blocks towards the completion of the AEC by 2028. With the Treaty coming into force in 1994, African countries were expected to complete six consecutive regional integration steps which would lead to a fully integrated market at the continental level within a 34-year period.

These steps included (i) strengthening of intra-regional integration and the harmonization between the blocs; (ii) creation of regional blocs (that is, the Regional Economic Communities or RECs); (iii) establishment of free trade areas (FTAs) and customs unions in each the RECs; (iv) creation of a continental free trade area and customs union; (iv) creation of an African common market; and (vi) establishment of an African economic monetary union and a parliament. However, the process of having a regionally integrated Africa has not been smooth and linear, both within and across all of the RECs (Mevel and Karingi, 2012). FTAs are established components of regional integration and have been known to promote commodity trade and investment flows by creating an improved enabling environment for cross-border transactions (Kawai & Wignajara, 2008). The processes may also prompt diversion of trade and investment away from countries with less favourable business conditions (Yunling, 2010). Thus, the impact of FTAs widely differs across countries on account of a multitude of factors that impact the business environment. Intra-continental trade in Africa is the lowest among all other regions in the world. This poor trade performance is both a significant cause and an obvious effect of the poor social and economic development of the region. Another crucial factor that could explain the low intra-African trade are both trade and non-trade barriers to exchange of good and services. The recent progress with the establishment of AfCFTA as endorsed by 54 African countries in July 2019 is therefore reassuring, given its potential to reduce the presence of barriers to trade on the continent.

However, the economic impacts of an FTA are unlikely to be the same across participating countries. There will be winners, and there will be losers. To this point, an in-depth literature review by Stevens et al. (2015) concludes that FTAs have positive effects on trade growth in at least some cases; however, the picture is mixed, with a range of widely-varying estimated effects. Even for a country benefiting from the ratifying of an FTA, the gains will be unevenly spread across sectors. This implies that, while aggregate trade and development gains from AfCFTA are likely, little is known on inter-and intersectoral gains within individual countries as well as the disparate effects in different nations.

Read More Download PDF

Continental Integration & the Nigerian Economy: The Effect of the African Continental Free Trade Area on Medium Small and Micro-scale Enterprises in Nigeria

Executive Summary

Africa is at a historical crossroads. The launching of the operational phase of the African Continental Free Trade Area (AfCFTA) Agreement during the 12th Extraordinary Session of the Assembly of the African Union (AU) in Niamey, Niger on 7 July 2019 marks the most significant event in the decadeslong project of African integration. If managed efficiently, this newly formed market of 55 nations, 1.2 billion people, and an aggregate GDP of up to $6.7 trillion Purchasing Power Parity (PPP) has the potential to bring unprecedented stimulus to African economies by unlocking the historically low level of intra-continental trade and attracting long-term, stable investments from around the world.

While there is general optimism surrounding the promise of AfCFTA to support economic development, there must also be a recognition that, like all Free Trade Agreements (FTAs), the AfCFTA will inevitably create winners and losers. Whether for their own inefficiencies, or the sub-optimal business environments they may find themselves in, some businesses – or even entire sectors of national economies – will not be in a position to make the most from the expanded market opportunities and may be unable to compete with the influx of new competitors from other economies.

These were just some of the considerations that sparked considerable opposition to the deal in Nigeria prior to its signing. Unfortunately, there has previously been a general lack of data and information regarding how the national economy will react, leaving plenty of room for speculation. In this report, CSEA employs a two-pronged strategy to begin filling in the knowledge gap that exists about the possible effects of the AfCFTA on Nigeria’s economy.

First, we zero in on Nigeria’s Micro, Small, and Medium Enterprises (MSMEs). It is no overstatement to say MSMEs are the backbone of the Nigerian economy. In fact, more than 96 percent of all business – contributing to 75 percent of national employment – qualify for MSME status. No trade deal can be good for Nigeria without it benefiting at least the majority of MSMEs. Too little is known about how MSMEs will be affected by the introduction of continental free trade.

In the production of this report, we conducted a representative survey of more than 1,800 MSMEs in five Nigerian states that covered the country’s various sociocultural zones to evaluate MSME awareness and preparedness to take advantage of the AfCFTA Agreement. We also gauged their most urgent needs to make the most of the opportunities presented by AfCFTA and to recover efficiently from the impacts of the COVID-19 pandemic.

Through this process, we found a worrying degree of unawareness about AfCFTA. Two-thirds of MSMEs surveyed declared not knowing of the deal’s existence. This lack of knowledge is particularly acute among smaller businesses and can represent an enormous obstacle to the successful uptake of AfCFTA. The knowledge deficit is compounded by the reported under-utilization of previously-enteredinto FTAs as a result of their complicated compliance requirements. We therefore recommend a targeted, context-specific knowledge dissemination strategy as a key requirement for MSME success in a post-AfCFTA economy.

Among respondents aware of the Agreement’s existence, we found general optimism about businesses’ ability to make the most of its opportunities. Nevertheless, many were somewhat worried by the prospects of more competition and reported a strong need for government investment in electrification and general transport infrastructure to enable them to compete effectively. These problems are, of course, not new in Nigeria. Nevertheless, our findings reinforce the need for a national concentrated effort to ameliorate the business environment to ensure Nigeria thrives in the newly integrated continent.

Finally, the majority of businesses surveyed declared that, in their view, the most effective government relief strategy in the wake of the pandemic would be making business loans more readily available. While we do not take a position on the matter, the findings can certainly be beneficial to national policymakers as they plan the recovery strategy.

The second prong of this study takes a more general look at macroeconomic reactions and trade creation/diversion in the Nigerian economy as a result of AfCFTA. Here, we employed a Computable General Equilibrium (CGE) Model to simulate the general movements of the Nigerian economy, as well as those of other economies across the continent. Our result shows modest positive welfare gains to Nigeria with machinery, other transport, textile and metal products as well as textile industries accounting for most of the positive effects on real wage. Sectors with large tariff reductions recorded higher volume of trade. AfCFTA led to changes in pattern of trade flow across Africa. The African countries facing the possibility of the most gains from AfCFTA are Angola, Botswana, and Seychelles.

It is clear from both sections of this study that the mere signing of the AfCFTA Agreement will not guarantee increased economic prosperity in Nigeria on its own. There is therefore no room for complacency. In this report, we highlight some of the most salient issues that may arise from the implementation of the AfCFTA Agreement and contribute to the foundation and accessibility of knowledge required to effectively set this historic Agreement in motion.


This report was first published here

Read More Download PDF

Green Finance Mechanisms in Developing Countries: Emerging Practice

To counter the devastating impact of COVID-19, calls are growing for countries to ‘build back better’ in an effort to create a more inclusive and sustainable economy that is climate resilient. Africa is facing glaring development and climate risk challenges, but the post-COVID-19 recovery plan offers it an opportunity to revitalise its economy using a green framework. In particular, green finance mechanisms can be employed for the continent’s green recovery. The objective of this policy briefing is to explore best practices in channelling investment towards a green economic recovery to promote inclusive and sustainable investment. Examples of such best practices include investment infrastructure and renewable energy, green/environmental funds and other market-based mechanisms, ensuring stimulus investments focus on green fiscal reform, redirecting existing funding, greening the financial sector and developing green segments.

This article was first published on SAIIA

Read More Download PDF

Nigeria Economic Update (Issue 46)

Data from the National Bureau of Statistics (NBS) shows that the average price paid for premium motor spirit (petrol) by consumers increased by 10.79 percent year-on-year to N161.17 in October 2020 from N145.48 in October 2019.1 This increase can be attributed to the removal of fuel subsidy which is driven by the government’s inability to generate sufficient revenue to fund the subsidy.2 Going forward, pump price is expected to be market-determined, as pump prices will no longer be fixed. From an environmentally sustainable perspective, the subsidy removal is a commendable development in disincentivizing the use of fossil fuel and incentivizing the use of renewable energy while reducing the crowding out of public revenue. However, the subsidy reform is being introduced in a worsening economic climate with implications on the living standard of most citizens. The government can leverage on the opportunity presented by the pandemic to introduce additional structural reforms such as streamlining government Ministries, Departments, and Agencies (MDAs) in order to make resources available for development spending.

Read More Download PDF

Nigeria Economic Update (Issue 45)

The Federal Executive Council has ratified Nigeria’s membership of the African Continental Free Trade Area (AfCFTA) agreement ahead of the December 5, 2020 deadline.1 The AfCFTA, which comes into effect on the 1st of January 2021, aims to create a single market for goods and services in Africa that can potentially increase consumer and business spending to over $6.7 trillion by 2030.2 Nigeria with its substantial market, large labour force and the economy is likely to be a major beneficiary of the agreement. However, the Nigerian government in some instances has taken an anti-trade policy stance such as the closure of land borders with Benin, Niger, and Cameroon in order to curb the smuggling of food products, and the new import prohibition on Maize. As such, the government will have to improve its preparedness towards implementing the AfCFTA by identifying and achieving quick wins to enhance trade across borders. Another important policy objective is increasing the awareness of the AfCFTA among local businesses in order that they leverage on the increased market access.

Read More Download PDF

Nigeria Economic Update (Issue 44)

The manufacturing and non-manufacturing Purchasing Managers’ Index (PMI) for the month of October showed a slowing contraction relative to previous months, making it the 7th consecutive month both indices have been below the 50-index point benchmark.1 Manufacturing PMI increased from 46.9 index points to 49.4 index points while non-manufacturing increased from 41.9 index points to 46.8 index points, but still below the 50-index point benchmark. However, 6 out of 14 subsectors in the manufacturing sector recorded an expansion relative to the previous month. In the non-manufacturing sector, only 3 out of the 7 sub sectors recorded growth relative to the previous month. Production is expected to improve significantly as the economy rebounds and the festive season approaches, thus both manufacturing and non-manufacturing PMI are expected to advance towards the 50-index point benchmark. However, the increase in PMI, as a result of increased demand, is likely to be associated with rising inflation. As such, the Central Bank of Nigeria (CBN) should increase efforts towards addressing the rapid increase in the price of commodities.

Read More Download PDF

Nigeria Economic Update (Issue 43)

The International Monetary Fund (IMF) has projected that the GDP growth for Nigeria will shrink to -4.3 percent at the end of 2020 from 2.2 percent in 2019.1  The negative growth forecast is attributed to fall in oil prices, coupled with a reduction in crude oil production due to production cut agreement by Organization of Petroleum Exporting Countries and other major oil producers (OPEC+). Also, the decline in domestic demand owing to the lockdown is another driver of the negative outlook. Growth is however projected to rebound in 2021 at 1.7 percent, when crude oil price and production increases. The pandemic has exposed the vulnerabilities of Nigeria’s mono-product economy and emphasized the need for diversifying the revenue base of the economy. Efforts towards boosting the performance of non-oil sectors such as agriculture, mining and entertainment should be increased and time-sensitive.

Read More Download PDF